The Digital Currency Era: Fintech's Opportunities and Challenges
With the rapid development of blockchain technology and digital currencies, the global fintech industry is undergoing a profound transformation. From the gradual formation of regulatory frameworks to the accelerated advancement of central bank digital currencies, and further to technological innovation and application expansion, digital currencies have brought unprecedented development opportunities to fintech while also posing complex challenges.
Evolution and Maturation of Regulatory Frameworks
Major global economies are actively constructing regulatory frameworks adapted to the characteristics of digital assets, signaling the integration of digital currencies into the mainstream financial system. In 2024, the U.S. Securities and Exchange Commission (SEC) approved the first spot Bitcoin exchange-traded funds (ETFs), allowing native digital assets to enter sovereign financial systems on a large scale. Almost concurrently, the European Parliament overwhelmingly passed the Markets in Crypto-Assets (MiCA) regulation, establishing unified legal standards for the issuance, trading, and reserve management of stablecoins, with plans for it to apply starting in December 2024. In 2025, the new U.S. administration shifted to pro-crypto policies, actively promoting Bitcoin strategic reserves, stablecoin development, and real-world asset tokenization through a series of legislative reforms and official appointments. Hong Kong also launched its virtual asset trading platform licensing regime in 2024 and approved the first batch of licensed exchanges, followed by the Hong Kong Monetary Authority (HKMA) publishing its "Discussion Paper on Stablecoin Regulatory Framework," demonstrating a cautious yet open attitude towards digital assets.
Accelerated Development of Central Bank Digital Currencies (CBDCs)
Central banks worldwide are actively exploring and piloting central bank digital currencies (CBDCs), aiming to enhance payment efficiency, reduce costs, improve financial inclusion, and serve as digital representations of national or regional physical currencies. The programmability of CBDCs offers innovative avenues for monetary policy tools, such as embedding interest rates via smart contracts. International cooperation mechanisms like the mBridge multilateral CBDC project are driving the restructuring of global payment networks to improve cross-border payment efficiency and reduce transaction costs.
Technological Innovation and Application Expansion
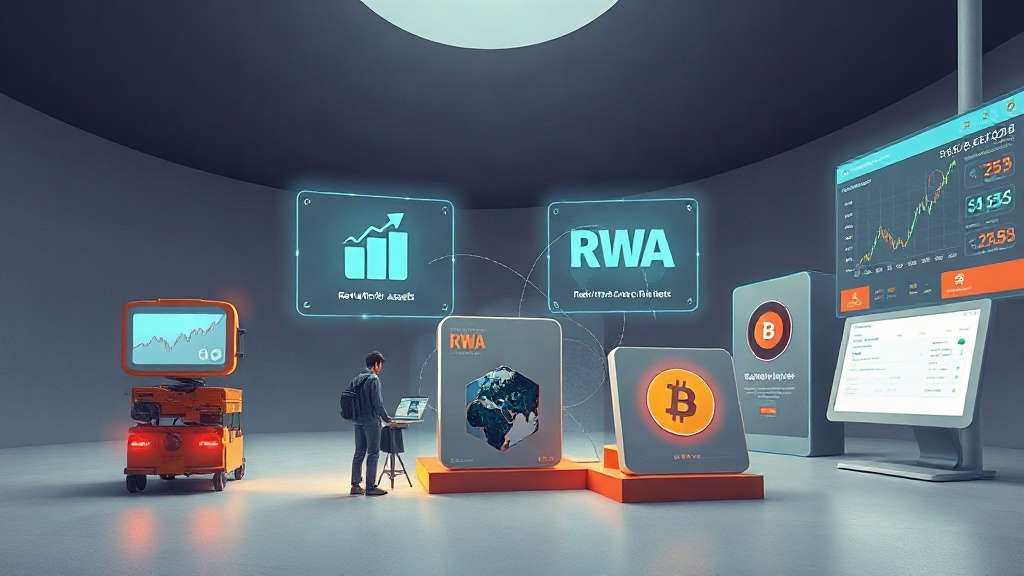
Blockchain technology continues to iterate, with emerging public chains like Solana (SOL) and Sui demonstrating significant advantages in performance, transaction throughput, and speed. Ethereum's smart contract functionality is widely applied in areas such as digital collectibles and the metaverse, giving rise to decentralized "on-chain digital asset markets." Tokenization of real-world assets (RWA) has become a significant trend, bringing traditional institutional assets onto the cryptocurrency rails and opening up new investment and liquidity channels. Decentralized finance (DeFi) transforms core financial activities like lending, trading, and payments into software, allowing any user with a crypto wallet to participate.
Market Dynamics and Global Adoption
Global adoption of digital currencies continues to grow. As of 2025, approximately 861 million people worldwide own or use cryptocurrencies, accounting for about 11.0% of the global population. As of June 2026, global cryptocurrency holders reached 774 million. In terms of market size, as of Q1 2026, the total global cryptocurrency market capitalization remained at $2.4 trillion, a decrease from its historical high of $4.4 trillion in October 2025. Investment in the fintech sector also remains active, with global fintech investment reaching $53 billion in 2025, a 21% year-over-year increase; in the first half of 2026, this figure further surged to $103.1 billion. Regarding cryptocurrency adoption rates, according to the Chainalysis 2025 index, India ranked first for the second consecutive year, followed by the United States, Pakistan, Vietnam, and Brazil. The 2026 Chainalysis index, however, shows Brazil in first place, the United States second, Nigeria third, and India dropping to sixth, reflecting dynamic shifts in the global adoption landscape.
Challenges and Multi-Stakeholder Perspectives
Despite numerous opportunities, fintech in the digital currency era also faces many challenges. While central banks and governments actively explore CBDCs, they remain highly concerned about money laundering, terrorist financing, capital flight, and potential financial stability risks associated with cryptocurrencies. Traditional financial institutions face challenges such as potential fund outflows and reduced deposit bases due to CBDCs, while also actively exploring the application of blockchain technology and digital assets. Regulatory bodies (such as the SEC, CFTC, FSA, HKMA, and the European Parliament) face challenges like legal lags, difficulties in cross-border cooperation, and insufficient technological adaptability as they strive to establish regulatory frameworks suited to digital currencies. Academia and international organizations (such as the IMF, BIS, and World Economic Forum) call for global regulatory cooperation and the establishment of unified standards to regulate market order and provide a safe space for innovation.
Conclusion
Fintech in the digital currency era is in a vibrant period of transformation. The gradual improvement of regulations, continuous technological innovation, and expanding application scenarios collectively form a solid foundation for industry development. However, the accompanying risks and challenges also require all parties to remain vigilant, guiding digital currencies and fintech towards a healthier, more sustainable future through international collaboration and prudent policy-making.